
How to Appeal an Insurance Denial
Insurance denials for addiction treatment are common, and frequently overturned on appeal. A denial is not a final answer. It is the beginning of a process that families who know their rights can often win. This guide walks through every step of that process, from internal appeal through external review and regulatory complaint.
Medically Reviewed by:
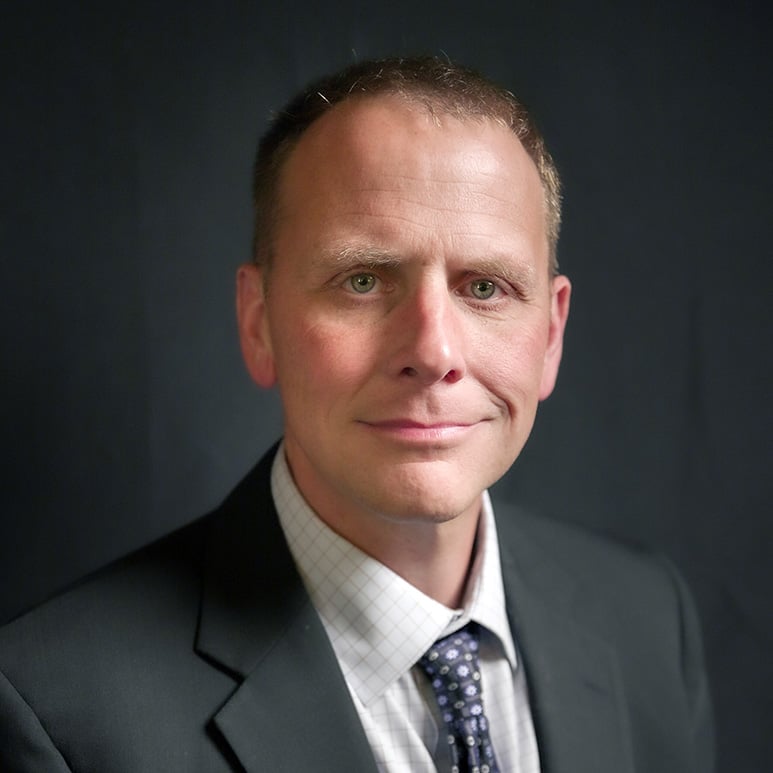
Dr. Darrin Mangiacarne
Chief Medical Officer
At Banyan Treatment Centers, Chief Medical Officer Dr. Darrin Mangiacarne leads our nationwide clinical team with over a decade of addiction medicine experience, helping ensure evidence-based, compassionate care across every level of treatment.
Author / Written by: Banyan Editorial Staff
Medically reviewed by: Dr. Darrin Mangiacarne, CMO
Updated on: September 2026
Family Resources Hub › Substance Use Resources › How to Appeal a Health Insurance Denial
Insurance denials for addiction treatment are common, and some are overturned on appeal. A health insurance denial is not always the final answer. It can be the beginning of a review process that gives patients and families the right to appeal a coverage decision.
This guide walks through the main steps of that process, from an internal appeal through external review and, when appropriate, a regulatory complaint. The exact process depends on the health plan, the reason for the denial, and the type of coverage involved.
Why Insurance Denies Addiction Treatment and Why Appeals Work
A health insurance denial for addiction treatment can happen for a few common reasons: the treatment is determined not to be medically necessary, the requested level of care does not meet the health plan's criteria, the provider is not in-network, prior authorization is missing, or the service is excluded from the plan. One common reason is "not medically necessary," meaning the health insurer has determined that the clinical documentation does not meet its criteria for the requested level of care.
The important thing to understand is that an insurance denial does not necessarily mean the decision is final. A denial may result from incomplete clinical documentation, differences in how medical necessity criteria are applied, or questions about whether mental health and substance use disorder benefits are being administered consistently with applicable parity requirements. Patients and their treatment providers may have the right to appeal a denied claim or coverage decision.
When an insurance company denies a claim or treatment request, the denial notice should explain the reason for the decision and provide information about the plan's appeal process. Depending on the type of health insurance coverage and denial, the process may include an internal appeal and, when eligible, an external review.
Do not automatically accept the first denial as final. Review the denial letter, understand the reason given, and determine what appeal rights apply to your specific health plan. Treatment providers, patient advocates, and other professionals familiar with insurance disputes may be able to assist with documentation and the appeal process.
Got a Denial? Our Team Has Done This Before — Call Us.
Banyan's admissions team can help you understand an insurance denial, identify documentation that may be needed, and navigate the applicable appeal process with you.
855-722-6926Free & confidential · Available 24/7 · No commitment required
How to Appeal a Health Insurance Denial
If you're wondering how to appeal a health insurance denial, the specific steps depend on your health plan, the reason for the denial, and the type of coverage you have. The process may involve several levels of review. Follow the instructions in your denial notice and document communications, forms, medical records, and other information you submit throughout the process.
Peer-to-Peer Review — Request This First
Depending on the insurance carrier and type of denial, a peer-to-peer review may be available before or as part of a formal appeal. This is a direct conversation between your loved one's treatment provider, such as a physician or clinical director, and the insurance company's physician reviewer or other medical reviewer. It gives the treatment provider an opportunity to explain the clinical reasoning supporting the requested treatment or level of care.
How to request it: Contact member services using the number on your insurance card and ask whether a peer-to-peer review is available for the denial. If it is, ask how to request one and whether there is a deadline. Treatment programs may also be able to handle or assist with this request on the patient's behalf.
What to have ready: The treating clinician should be prepared to discuss the specific clinical criteria supporting the requested level of care, co-occurring diagnoses, safety concerns, and why a lower level of care may be clinically insufficient. Relevant medical records and assessments can also help document medical necessity.
Internal Appeal — The Formal First Step
If a peer-to-peer review is unavailable or does not resolve the denial, the next step may be to file a formal internal appeal with the insurer. For many health plans subject to federal requirements, appeal deadlines and insurer response timeframes depend on whether the claim involves urgent care, a pre-service request, or a post-service claim. Review your denial notice and plan documents carefully for the deadlines that apply to your coverage.
Your internal appeal letter should include:
- A clear statement of what you are appealing and why you believe the treatment or services should be covered
- A clinical letter from the treatment provider documenting the criteria supporting the requested level of care
- The insurer's stated criteria and an explanation of why the patient meets them
- When applicable, a request for information about how relevant mental health or substance use disorder coverage criteria comply with parity requirements
- Relevant clinical notes, assessments, medical records, or documentation of prior treatment history
Important: Follow the submission instructions provided by your health plan and keep copies of the appeal letter, forms, supporting documentation, and confirmation that the insurer received your appeal.
External Appeal — Independent Review
If the internal appeal is unsuccessful, you may be eligible for an external appeal or external review. During the external appeal process, an outside reviewer evaluates the coverage decision rather than relying solely on the health insurer's internal review.
Eligibility, deadlines, and procedures for external review vary according to the type of health plan and applicable state or federal requirements. Your final internal denial notice should provide information about whether you are eligible for external review and how to request it.
- For individual and fully insured plans: Review the denial notice and contact your state's Department of Insurance or other designated agency for information about the applicable external review process.
- For employer-sponsored plans: Review the plan documents and denial notice to determine the applicable external review procedure. Depending on the plan, an independent review organization may evaluate eligible disputes.
Include relevant documentation from your internal appeal, the insurer's denial letter, and any additional clinical information that supports why the requested treatment is medically necessary.
Regulatory Complaints — Parallel Track
Depending on the type of health insurance coverage and the nature of the dispute, consumers may also have the option to file a complaint with an appropriate state or federal agency. A regulatory complaint is separate from an insurance appeal and does not necessarily replace the plan's required appeal process.
- State insurance department: For many individual, marketplace, and fully insured group plans, contact your state's Department of Insurance or insurance regulator.
- Department of Labor (EBSA): For questions or complaints involving many employer-sponsored health plans, contact the U.S. Department of Labor's Employee Benefits Security Administration.
- State Medicaid agency: For Medicaid managed care coverage disputes, review the denial notice and contact the state Medicaid agency for information about appeal and fair-hearing rights.
- State attorney general: Depending on the circumstances, a state attorney general's office may provide information about consumer protection complaints or other available resources.
What to Gather Before You File
From the Treatment Provider
- Letter of medical necessity citing the clinical criteria supporting the requested treatment
- Clinical assessments and diagnostic documentation
- Documentation of co-occurring mental health conditions
- Prior treatment history and outcomes
- Safety and risk assessment
- Specific explanation of why a lower level of care may be clinically insufficient
From Your Records
- The insurer's denial letter or denial notice with the specific reason for denial
- Your insurance card and policy or health plan documents
- Notes from your benefits verification call, including the date, time, representative's name, and reference number
- Any prior correspondence with the insurance company
- Summary Plan Description, when applicable to an employer-sponsored plan
- Prior authorization documents, if any were submitted
Speak With an Admissions Specialist
Fill out the form below and a member of our team will reach out within one business hour, confidentially and without pressure.
Related Guides
Does Insurance Cover Addiction Treatment?
What the law requires insurers to cover and how to understand your benefits before treatment begins.
Read the guide →The Mental Health Parity Act
Your legal rights when insurers apply more restrictive standards to addiction treatment than to other medical care.
Read the guide →How to Verify Insurance Benefits for Rehab
The questions to ask and records to keep before treatment starts — the foundation of any appeal.
Read the guide →Inpatient vs. Outpatient Rehab
Understanding levels of care — the clinical basis for medical necessity documentation in an appeal.
Read the guide →What If I Can't Afford Treatment?
Options when insurance falls short — including Medicaid, sliding-scale fees, and financing.
Read the guide →How Long Does Rehab Last?
What research says about treatment duration — and why advocating for longer care often means appealing short authorizations.
Read the guide →Additional Resources
Tools, community, and organizations to support your family's journey.
Crisis & Hotlines
Immediate help — national helplines and crisis resources for addiction and mental health emergencies.
View all crisis resources →Support Groups
Al-Anon, Nar-Anon, SMART Recovery Family & Friends, and peer groups for families.
Find a group near you →Blog & Articles
Clinician-authored articles, personal stories, and recovery news to keep families informed.
Read the Banyan blog →Insurance & Financing
Insurance verification, financing options, and navigating the cost of treatment.
Check your coverage →Downloadable Guides
Free PDFs on intervention, what to pack for treatment, and relapse prevention planning.
Free family addiction guide →About Banyan
Our clinical approach, accreditations, and the team behind Banyan's family-centered care model.
Meet our clinical team →